The rear driver often causes a Texas rear-end crash, but vehicle position alone does not decide payment. The evidence must show who acted negligently and which insurance policies cover the loss.
Cowen | Rodriguez | Peacock car accident attorney investigates before insurers lock injured people into an incomplete account. We secure vehicle data, video, phone records, witnesses, and insurance information, then prepare serious claims for trial when the carrier refuses to pay the full loss.
What Matters Most After a Texas Rear-End Crash
- The rear driver’s liability insurer usually pays when unsafe following distance, distraction, speeding, or delayed braking caused the collision.
- Texas does not make the rear driver automatically responsible in every case. The lead driver or another motorist can share fault.
- PIP, collision, and uninsured or underinsured motorist coverage can provide additional payment when the at-fault policy is delayed or insufficient.
- A rear-end claim can include medical expenses, lost income, vehicle damage, diminished value, pain, impairment, and other proven losses.
- Texas generally gives injured people two years to file suit, but video and electronic evidence can disappear within days or weeks.
Who pays after a rear-end collision in Texas?
The driver who caused the crash is responsible for the resulting losses, and that driver’s liability insurer usually pays, although your own PIP, collision, or uninsured motorist coverage can apply while fault or coverage is disputed.
Who Pays for a Rear-End Collision in Texas?
The person or company responsible for causing the crash must pay the resulting damages. In most cases, an auto liability insurer handles that payment up to the available policy limits.
The At-Fault Driver’s Liability Insurance
The rear driver’s insurer usually pays when unsafe following distance, distraction, excessive speed, or delayed braking caused the crash.
Texas Transportation Code Section 545.062 requires drivers to maintain enough clear distance to stop safely based on speed, traffic, and highway conditions. A failure to use reasonable care under those conditions can support a negligence claim.
Liability coverage can pay for:
- Medical expenses
- Lost income
- Pain and physical impairment
- Vehicle repair or replacement
- Rental transportation
- Other property damage
A citation or rear impact alone does not force payment. We build the proof connecting the driver’s conduct to each claimed loss.
Your Own Auto Insurance
Your policy can provide payment before the liability dispute ends or when the at-fault driver lacks enough insurance. The exact benefits depend on the coverages you purchased.
The Texas Department of Insurance auto insurance guide explains that:
- Personal injury protection can pay medical bills, lost income, and certain nonmedical expenses.
- Collision coverage can pay for vehicle repairs or replacement, subject to a deductible.
- Uninsured or underinsured motorist coverage can apply when the responsible driver has no insurance or insufficient limits.
- Medical payments coverage can pay qualifying medical bills for you and your passengers.
Using your own coverage does not transfer fault to you. Your insurer can pursue reimbursement from the responsible carrier.
An Employer or Business Policy
A commercial policy can pay when the rear driver was performing assigned work. Delivery drivers, sales employees, contractors, rideshare drivers, and other workers can create claims against business-related coverage.
We examine ownership, work assignments, app status, dispatch information, and the driver’s relationship with the company. Commercial activity can make employer or platform coverage central to recovery.
Is the Rear Driver Always at Fault in Texas?
The rear driver is not automatically at fault. Rear-end collision fault in Texas depends on each driver’s conduct and the events immediately before impact.
Texas courts have held that a rear impact can support a negligence claim, but it does not establish negligence as a matter of law. The injured person must still prove specific negligent conduct and show that it caused the losses.
Unsafe Following Distance Often Establishes Rear-Driver Fault
A driver must leave enough room to respond when traffic slows or stops. Tailgating, distraction, speeding, fatigue, and failure to account for rain or congestion can establish negligence.
Evidence of rear-driver fault can include:
- No meaningful skid marks before impact
- Phone activity near the crash time
- Event data showing late braking
- Witnesses who saw close following
- Dashcam or surveillance footage
- Statements admitting distraction
- Severe rear impact despite visible traffic
The Front Driver Can Share Responsibility
The lead driver can share fault when that driver creates an unreasonable hazard. Examples include reversing into another vehicle, entering a lane without enough space, driving without working brake lights, or stopping in a travel lane without a valid reason.
A sudden stop alone does not make the front driver liable. Drivers must anticipate ordinary changes in traffic. The question is whether each person used reasonable care.
Another Driver Can Cause the Impact
A third vehicle can push one car into another, creating a chain-reaction collision. A defective vehicle component, unsafe roadway condition, or company-owned vehicle can also expand the liability investigation.
We reconstruct the impact sequence before deciding who pays. Damage patterns, vehicle data, and witnesses often reveal whether one or several impacts occurred.
What Evidence Proves Who Is at Fault in a Rear-End Accident?
The strongest rear-end collision claims combine physical, electronic, and human evidence. A police report helps, but it rarely contains every fact needed to defeat an insurance defense.
Vehicle Damage and Electronic Data
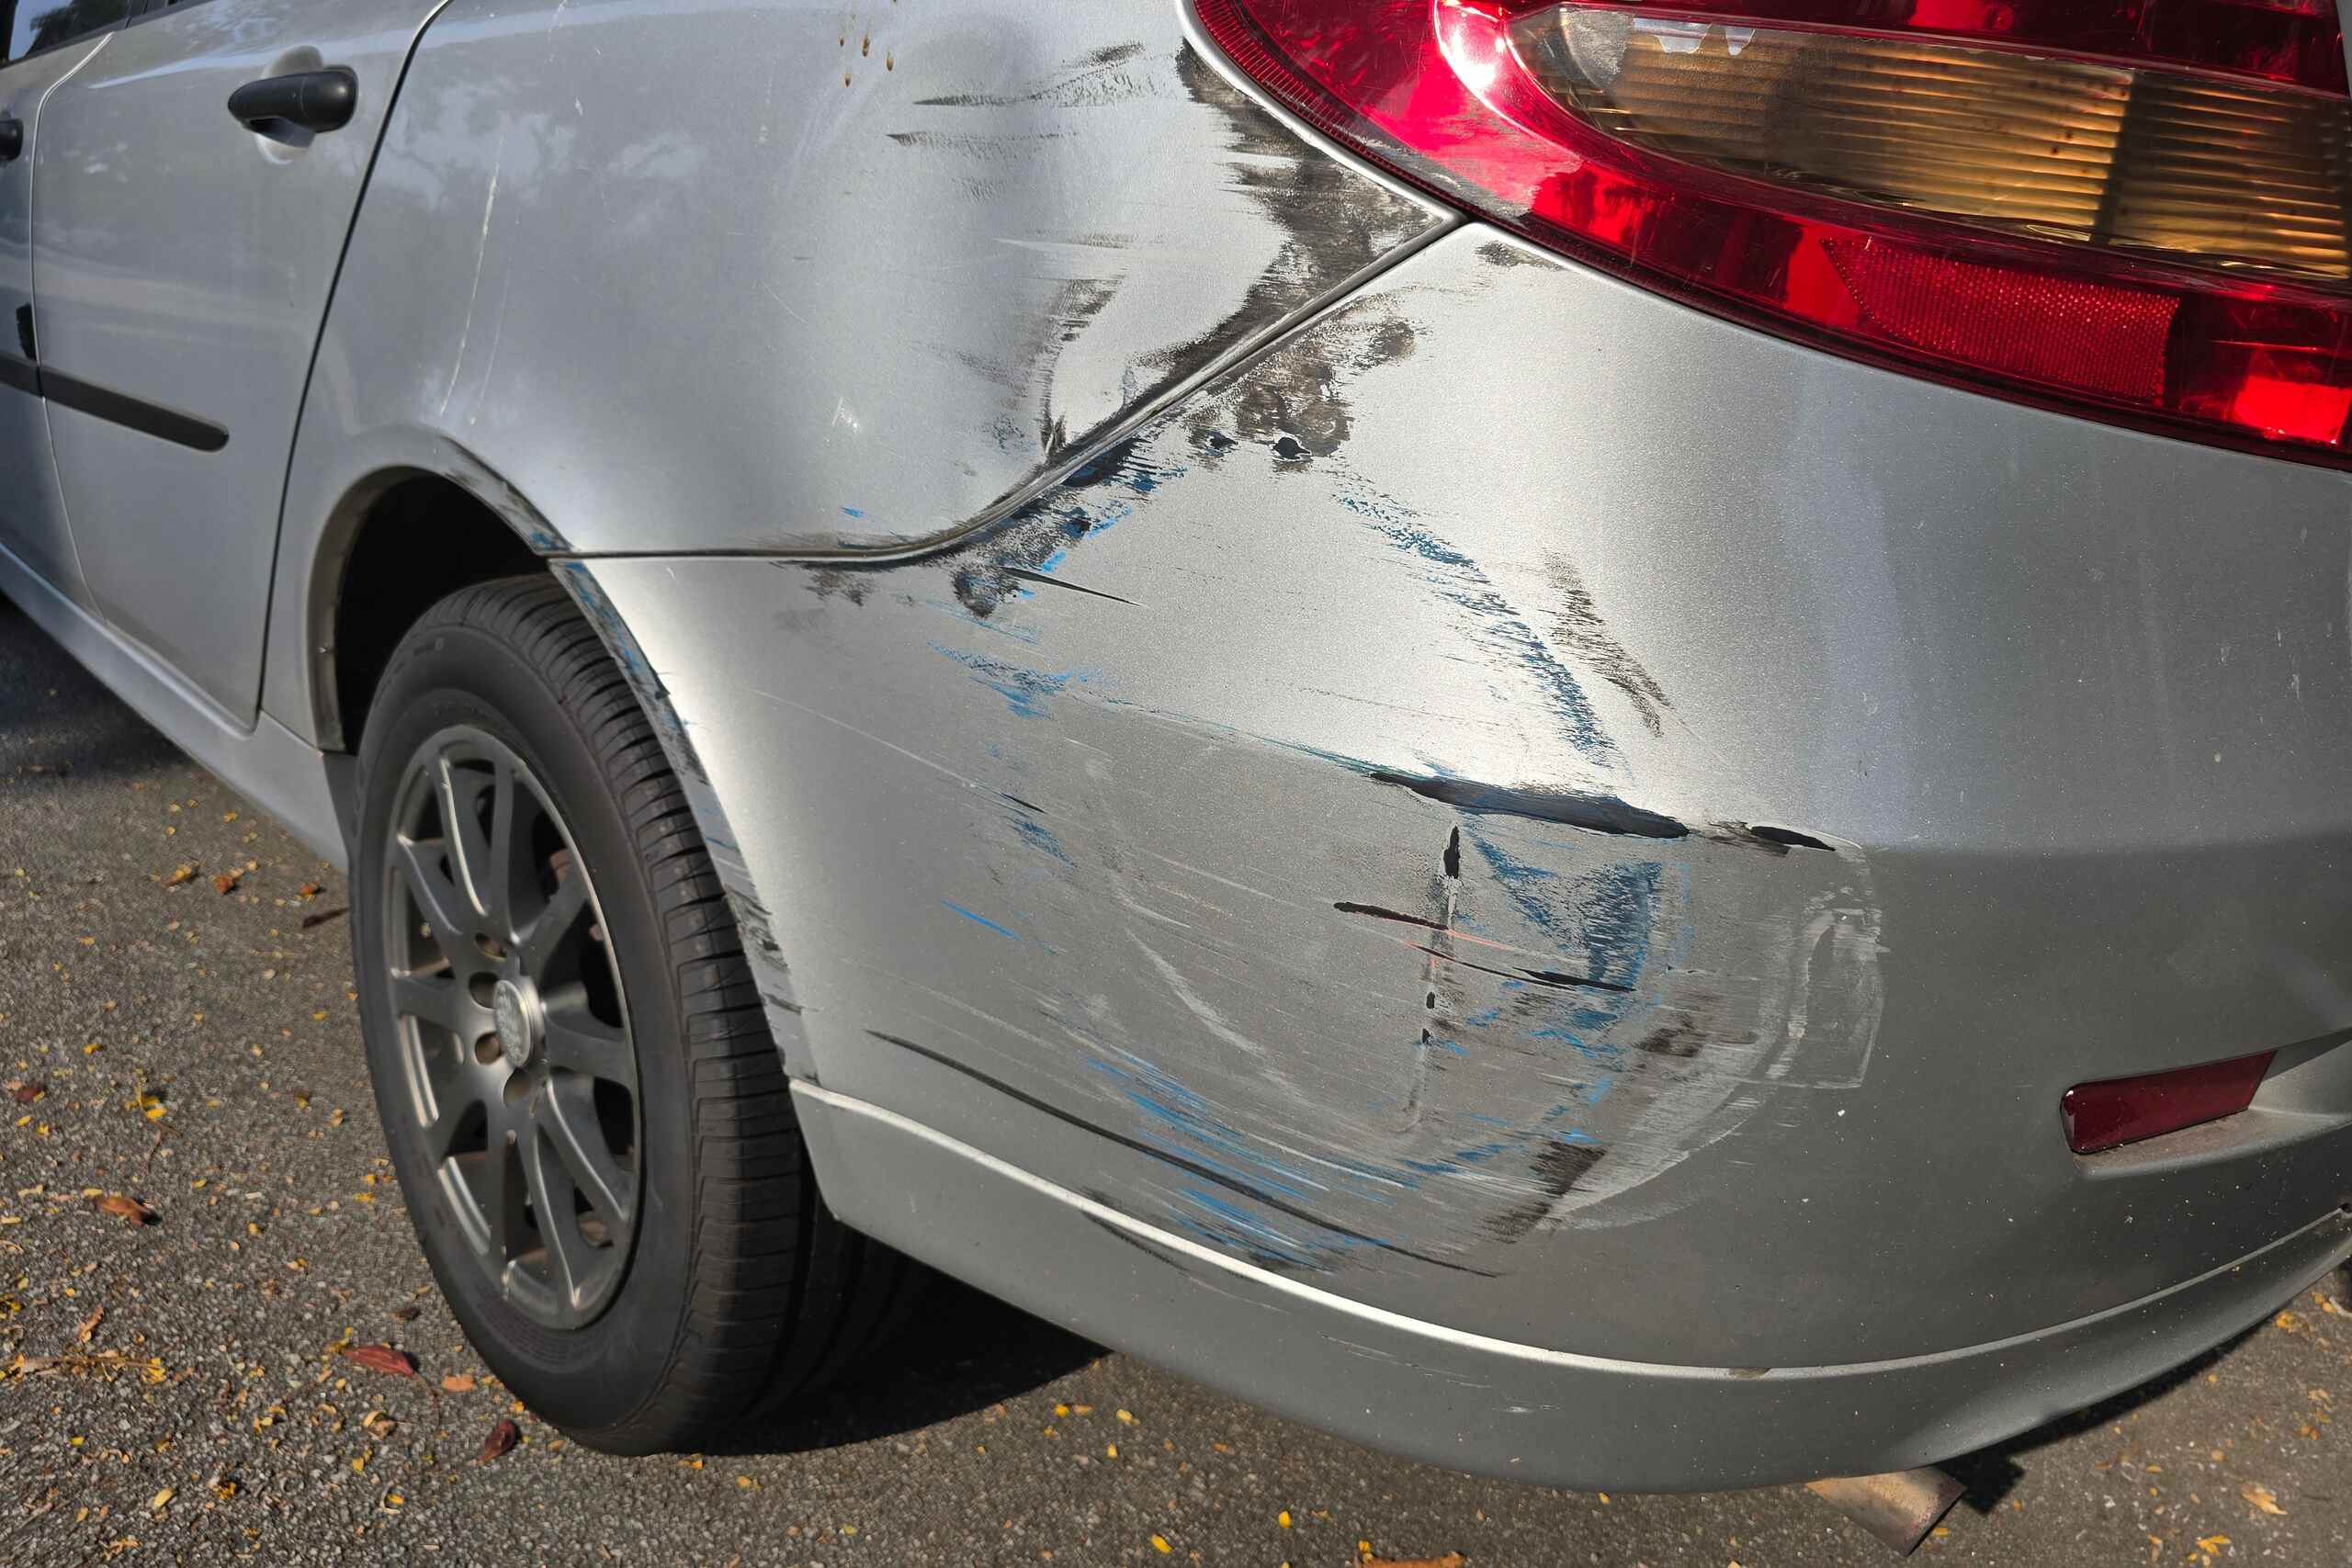
Damage location and crush patterns help establish the direction and force of impact. Modern vehicles can also store information about speed, braking, throttle position, and seat-belt use in the seconds surrounding a crash.
We pursue:
- Event data recorder information
- Photographs taken before repairs
- Repair estimates
- Total-loss evaluations
- Vehicle inspections
- Dashcam footage
- Tow-yard records
Vehicles can be repaired or destroyed quickly, making early preservation important.
Video, Phone Records, and Witnesses
Traffic cameras, nearby businesses, doorbell cameras, and other vehicles can capture the collision or the moments before it. Phone records can establish calls, texts, app use, or location activity.
Witnesses can describe following distance, brake lights, lane changes, and the impact sequence. Their information matters because memories fade.
Medical and Employment Records
Fault determines who pays, but documentation determines how much the claim supports. Medical records connect the collision to the treatment, while employment records establish missed income and reduced work capacity.
We also use photographs, receipts, calendars, and testimony about changes in daily life. A complete file prevents the insurer from valuing the case from early bills alone.
What Compensation Is Available After a Texas Rear-End Collision?
A successful rear-end claim can recover economic and noneconomic losses. The amount depends on fault, injuries, documentation, policy limits, and long-term impact.
| Type of Loss | What the Claim Can Include |
| Medical costs | Emergency care, surgery, rehabilitation, medication, equipment, and future treatment |
| Income losses | Missed wages, lost business income, reduced hours, and diminished earning capacity |
| Vehicle losses | Repairs, total-loss value, towing, storage, rental costs, and diminished value |
| Personal losses | Physical pain, mental anguish, impairment, and disfigurement |
| Fatal crash losses | Wrongful death damages and qualifying survival claims |
Injury-Related Losses
A serious claim must account for current and future consequences. Settling from early bills alone can leave later treatment, work restrictions, and long-term limitations unpaid.
We pursue evidence of future costs and reduced earning capacity, including medical, vocational, economic, and employment proof.
Vehicle Damage and Diminished Value
Repairing a vehicle does not erase its collision history. A newer vehicle can lose resale value even after quality repairs, creating a separate diminished value claim against the at-fault carrier.
Repair records, market comparisons, and an independent appraisal can establish diminished value. A total-loss claim focuses on the vehicle’s pre-crash market value.
How Does Shared Fault Affect Who Pays?
Texas reduces compensation when the injured person shares responsibility. A claimant can recover when that person is 50 percent or less at fault, but the award is reduced by the assigned percentage. A person found more than 50 percent responsible cannot recover under Texas proportionate responsibility law.
Insurance Companies Use Shared Fault to Reduce Payment
A rear-driver insurer can argue that the front driver stopped abruptly, changed lanes, had defective brake lights, or failed to avoid the impact. These arguments directly affect settlement value.
We test each allegation against:
- Vehicle data
- Video
- Brake-light condition
- Lane markings
- Traffic flow
- Witness accounts
- The rear driver’s speed and following distance
An adjuster’s percentage is a negotiating position, not a binding legal decision.
Fault Percentages Change the Final Recovery
A claimant with $200,000 in proven damages who is found 20 percent responsible can recover $160,000. A claimant found 51 percent responsible cannot recover.
Even a small shift in fault can change who pays and how much compensation remains available.
What Should You Protect in the Days and Weeks After the Crash?
The days and weeks after a rear-end collision should focus on treatment, documentation, and preserving evidence. Small gaps give insurers room to question both fault and damages.
Consider keeping:
- Medical bills and appointment records
- Prescription and transportation receipts
- Wage statements and missed-work records
- Repair estimates and total-loss documents
- Photographs of vehicle damage and visible injuries
- Insurance letters, emails, and recorded-statement requests
- Witness names and contact information
- Notes about activity limits and missed responsibilities
Be Careful With Early Insurance Requests
An adjuster can request a recorded statement before the investigation is complete. Questions about speed, stopping distance, prior conditions, treatment gaps, and current symptoms can later be used to limit payment.
Cowen | Rodriguez | Peacock handles insurer communications for our clients. We provide necessary information without allowing the carrier to define the case through a rushed interview.
Do Not Rush a Final Release
A settlement release usually ends the claim. Once signed, it can prevent further recovery even when additional treatment, lost income, or complications appear.
We evaluate liability, coverage, treatment, work impact, liens, and future losses before recommending a resolution. We prepare for trial when the insurer refuses to pay the full claim.
How Long Do You Have to File a Rear-End Collision Claim?
Texas generally gives an injured person two years from the collision date to file suit. Property damage claims usually follow the same period, but exceptions can change the deadline.
Evidence Has a Much Shorter Life
The lawsuit deadline does not preserve:
- Surveillance recordings
- Vehicle data
- Phone records
- Witness memories
- Damaged vehicles
- Rideshare app information
- Company driving records
We begin preservation work before those materials disappear. A timely lawsuit cannot recreate evidence that was lost months earlier.
Texas Rear-End Collision Questions Answered by Our Attorneys
Who pays if the rear driver has no insurance?
Your uninsured motorist coverage can pay qualifying injury and property losses when the responsible driver has no insurance. Collision, PIP, medical payments, and health coverage can also provide benefits depending on the policy.
Can a passenger recover compensation after a rear-end crash?
A passenger can pursue compensation from any driver or company whose negligence caused the collision. The passenger’s claim can include medical costs, lost income, pain, impairment, and other proven losses.
Does the rear driver have to receive a ticket for me to file a claim?
No. A citation is not required to prove civil negligence. Video, vehicle data, physical damage, witness statements, and the driver’s own admissions can establish fault even when the officer issued no ticket.
Who pays for a rental car after a rear-end collision?
The at-fault driver’s property damage coverage can pay reasonable rental costs while the vehicle is repaired or until a total-loss payment is made. Your rental reimbursement or uninsured motorist coverage can provide another option when the liability carrier delays or disputes fault.
Can I recover if the crash aggravated an older injury?
Yes. A driver can be responsible for worsening a preexisting condition. Medical records, imaging, provider opinions, and evidence of your abilities before and after the collision can separate the prior condition from the new harm.
When the Insurance Company Refuses to Pay
Rear-end crashes look simple until the insurer disputes fault, minimizes the injuries, or points to limited coverage. That is when evidence and trial preparation control the outcome.
Cowen | Rodriguez | Peacock investigates the collision, pursues every responsible driver and company, and identifies every available insurance policy. Our clients speak directly with an attorney, not only a case manager.
Call Cowen | Rodriguez | Peacock at (210) 941-1301 for a free consultation. We are available 24/7, and there is No Cost to You unless we win.